

Updated September 2026 — reflecting current Florida housing market conditions, active DPA program terms, and the 2026 wholesale rate environment. Verify FL Assist, FL HLP, and Salute Our Soldiers program terms directly at floridahousing.org, as parameters and funding availability are subject to change.
OG & Social Meta Audit (site operators): Confirm og:title, og:description, og:image, twitter:card, twitter:title, and twitter:description are fully populated in the page head for this article. Complete Open Graph and Twitter Card tags are required on every published page — a confirmed gap in prior site audits that must not recur.
Shopping for a home in Florida while protecting your credit score is not a contradiction. A soft credit pull mortgage pre-approval — also called a no-hard-inquiry pre-qual, soft inquiry mortgage screening, credit-safe mortgage consultation, or no-touch credit check — lets you see real loan options, estimated eligibility, and program compatibility, all without the ding that comes from a traditional hard inquiry. That matters in a state where property insurance costs, flood zone designations, and county-level income limits can shift your qualification picture significantly before you ever submit a formal application.
In 2026, Florida’s housing market remains active: 30-year fixed rates for well-qualified borrowers generally range from the mid-6% to low-7% range, inventory has shifted in select markets, and down payment assistance programs remain a meaningful lever for qualified buyers. An independent mortgage broker with access to 500+ wholesale lenders can simultaneously shop your profile across the full lender landscape — covering VA, FHA, USDA, conventional, and non-QM programs — using just a soft pull, with no hard inquiry until you choose to move forward. That multi-lender reach is something no single retail bank or direct lender can replicate.
Key programs available through the soft-pull pre-qualification process include Florida Housing Finance Corporation’s FL Assist (up to $10,000 at 0% interest, deferred), FL HLP (up to $10,000 at 3% interest, 15-year amortizing, ~$69/month), and the Salute Our Soldiers Military Mortgage Program — plus broker-exclusive programs Dynamo DPA and Turbo DPA — all of which can help qualified buyers arrive at closing with little to nothing out of pocket at closing. Eligible veterans and active-duty service members can qualify for VA financing with credit scores as low as 500 FICO through specialized wholesale lenders — well below the 580–620 overlays most retail lenders impose. And with 1,400+ five-star reviews across verified platforms, the track record of Florida-specific broker guidance is documented and measurable.
Multiple hard inquiries in a short window can chip away at the score you need to qualify for the best rate. The tools and approaches below let you do the groundwork first. Whether you’re a first-time buyer in Orange County, a homeowner exploring a cash-out refinance in Hillsborough, or a veteran weighing VA loan options anywhere in Florida, the right starting point protects your credit while giving you real answers.
Written by Duane Buziak, NMLS #1110647, Coast2Coast Mortgage LLC NMLS #376205 — Florida-licensed mortgage broker serving clients statewide.
1. Florida Mortgage Maestro — NoTouch Credit Pull Pre-Approval
Best for: Florida buyers who want real lender options across 100+ sources without a credit score impact.
Florida Mortgage Maestro is a Florida-licensed mortgage broker process that uses Vantage Score 4.0 to assess eligibility across hundreds of lenders simultaneously — with no hard inquiry on your credit report until you choose to move forward.
Where This Tool Shines
Most pre-approval processes require a hard inquiry before you see a single rate. The NoTouch Credit Pull flips that sequence. You find out what you qualify for, which programs apply, and what your payment range looks like — then you decide whether to proceed. That’s a meaningful protection when your score is sitting near a pricing tier boundary.
The simultaneous multi-lender shopping is the other differentiator. Rather than approaching lenders one by one (each potentially triggering its own inquiry), a single soft-pull session here covers the full lender landscape. Florida’s no state income tax means your gross income isn’t reduced by state withholding, which can genuinely improve your debt-to-income ratio compared to borrowers in income-tax states — and this process accounts for that Florida-specific advantage when modeling eligibility.
Key Features
Vantage Score 4.0 Soft Pull: No credit score impact at the eligibility stage — the model developed jointly by Equifax, Experian, and TransUnion is used to assess qualification without a reportable hard inquiry.
100+ Lender Simultaneous Shopping: One session, hundreds of lenders evaluated — no need to repeat the process with each source.
Florida-Licensed Statewide: Serves buyers across all Florida counties remotely — never requires an in-person visit.
Program Compatibility: Compatible with FL Assist, FL HLP, VA, FHA, USDA, and conventional programs — eligibility is checked against the full spectrum, not just one loan type.
Cash-Out Refinance to 90% LTV: Homeowners exploring equity access can use the same soft-pull process before committing to a formal application.
24/7 Availability and Fast Close Times: Available around the clock with some of the fastest close timelines in the Florida market.
Best For
First-time buyers who need to understand their options before committing. Homeowners considering a cash-out refinance who want to model scenarios first. Veterans and active-duty borrowers who want to layer VA eligibility on top of a multi-lender comparison. Anyone who has been told their credit score is “borderline” and wants real answers without the risk of another inquiry.
Pricing
No fee for the soft-pull eligibility check. Broker compensation is disclosed on the Loan Estimate per federal RESPA requirements — no hidden costs at the eligibility stage.
2. CFPB Loan Estimate Explainer Tool
Best for: Buyers who want to understand and compare Loan Estimates from multiple lenders on equal footing.
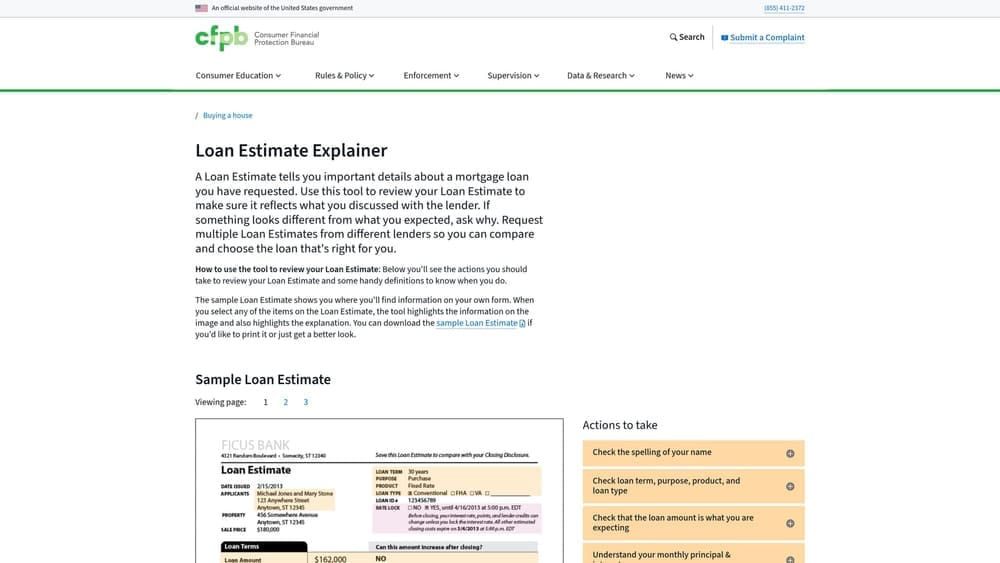
The CFPB Loan Estimate Explainer is the Consumer Financial Protection Bureau’s free, official interactive guide to reading every line of a standard Loan Estimate — the disclosure every mortgage lender must provide within three business days of application.
Where This Tool Shines
Once you have Loan Estimates in hand from one or more lenders, this tool becomes your decoder ring. It walks through every field in plain language — APR versus interest rate, origination charges, points, prepaid items, and cash-to-close figures — so you’re comparing apples to apples rather than being confused by lender-specific formatting.
For Florida buyers navigating multiple program types (FHA vs. conventional vs. VA vs. DPA-layered loans), the ability to read a Loan Estimate accurately is not optional. A lower rate on one estimate can be offset by higher origination fees or points. This tool makes that visible without requiring any financial background.
Key Features
Line-by-Line Explanation: Every field on a standard Loan Estimate is explained in plain language — no guessing what “origination charges” actually means.
Interactive Format: Click any section of the sample Loan Estimate to get an immediate, plain-language definition.
APR vs. Interest Rate Clarity: Explains why these two numbers differ and which one matters more for comparison shopping.
No Login, No Credit Pull: Completely free, no registration, no personal information required.
Comparison Framework: Helps buyers evaluate competing offers on the same standardized form — critical when comparing broker quotes against bank quotes.
Best For
Any buyer who has received a Loan Estimate and isn’t sure how to read it. Particularly useful for first-time buyers comparing offers from multiple sources after using a soft-pull pre-approval process to generate initial options.
Pricing
Free. Government resource operated by the Consumer Financial Protection Bureau — no registration required.
3. Florida Housing Finance Corporation — Program Eligibility Portal
Best for: Florida buyers checking income limits and purchase price caps for state DPA programs before applying.
Florida Housing Finance Corporation is the official state portal for Florida’s homebuyer assistance programs — including FL Assist, FL HLP, and Salute Our Soldiers — allowing buyers to check eligibility parameters without initiating a formal application or triggering any credit inquiry.
Where This Tool Shines
Florida’s down payment assistance programs are county-specific. Income limits and purchase price caps vary by location, household size, and program year. Checking these figures before you start the formal process saves time and prevents the disappointment of discovering you’re over-income after a hard pull has already been recorded.
Florida’s no state income tax is a genuine advantage here: because state tax withholding doesn’t reduce your gross income, Florida buyers may find they fall within income limits more comfortably than they expect. The portal also identifies participating lenders and brokers — confirming which sources are approved to originate these programs before you invest time in a conversation.
Key Features
Income and Purchase Price Cap Lookup: County-specific figures — no credit pull, no application, no commitment.
FL Assist Details: Up to $10,000 at 0% interest, deferred second mortgage — no monthly payment on the assistance itself. Verify current terms at floridahousing.org.
FL HLP Details: Up to $10,000 at 3% interest, 15-year amortizing second mortgage — does carry a monthly payment, which affects DTI calculations.
Salute Our Soldiers Program: Designed for eligible veterans and active-duty service members — details and current terms available through the portal.
Participating Lender Directory: Confirms which brokers are approved to originate these programs — an important step before committing to a lender relationship.
Best For
First-time buyers in Florida who are considering down payment assistance. Buyers who want to confirm program eligibility before initiating a soft-pull pre-approval. Particularly valuable for buyers in counties with tighter purchase price caps — knowing the ceiling before you start shopping prevents wasted effort.
Pricing
Free to use. The DPA programs themselves may carry a rate premium depending on the program and current market conditions — verify current terms directly at floridahousing.org before assuming cost.
4. HUD Area Median Income (AMI) Lookup — huduser.gov
Best for: Verifying county-level income limits that govern FHA, USDA, and most Florida DPA program eligibility.
The HUD AMI Lookup Tool is the U.S. Department of Housing and Urban Development’s official dataset for county-level Area Median Income figures — the authoritative source used by lenders, housing agencies, and DPA program administrators to determine income limit thresholds.
Where This Tool Shines
Every major Florida assistance program ties its income limits to HUD’s AMI figures. If you’re trying to determine whether your household income qualifies for FL Assist, FL HLP, or USDA financing, this is the source those programs are actually referencing. Going directly to the source eliminates the guesswork that comes from third-party summaries that may be using outdated figures.
The household size adjustment is particularly important. AMI limits scale by household size — a two-person household has a different limit than a four-person household at the same income level. Florida buyers with larger households often qualify at higher income levels than they realize, especially when combined with the DTI advantage that comes from having no state income tax reducing take-home pay.
Key Features
County-Specific AMI Data: Every Florida county covered — from Miami-Dade to Escambia, with precise figures for the current program year.
Household Size Adjustments: Figures for one through eight-person households — allows precise limit calculation rather than rough estimates.
Annual Updates: Confirms current program year figures — important because AMI limits adjust annually and third-party sources often lag.
No Login, No Credit Pull: Free federal government dataset, no registration required.
Authoritative Source: Used directly by lenders and housing agencies — not an interpretation, the actual governing figures.
Best For
Any Florida buyer considering income-restricted programs — FHA, USDA, FL Assist, FL HLP, or Salute Our Soldiers. Essential for buyers near the income limit boundary, where a precise figure matters more than a rough estimate.
Pricing
Free. Federal government dataset operated by HUD — no registration required.
5. VA Loan Eligibility Center — VA.gov
Best for: Veterans, active-duty service members, and surviving spouses verifying VA home loan entitlement without a credit inquiry.
The VA Loan Eligibility Center is the official U.S. Department of Veterans Affairs portal for verifying VA home loan entitlement, obtaining a Certificate of Eligibility (COE), and understanding funding fee tiers — all without any credit pull.
Where This Tool Shines
The COE is the document that confirms your VA loan entitlement to a lender. Many veterans don’t realize they can obtain or verify this document online before ever speaking to a lender — which means you can confirm your VA benefit status as a clean starting point before initiating a soft-pull pre-approval conversation. Knowing your entitlement status (full versus remaining) shapes which loan scenarios are available to you.
The funding fee calculator here is genuinely useful for payment modeling. The fee varies based on down payment percentage, whether it’s a first or subsequent use of the VA benefit, and whether the borrower has a service-connected disability (which may exempt them from the fee entirely). Florida veterans using VA financing also benefit from the state’s no income tax advantage — that gross income figure, undiluted by state withholding, can meaningfully improve DTI calculations on VA loan scenarios.
Key Features
Certificate of Eligibility (COE) Request: Available online through VA.gov, by mail, or through a VA-approved lender — no credit pull required to verify entitlement.
Entitlement Verification: Confirms full versus remaining entitlement — important for veterans who have used VA financing before.
Funding Fee Calculator: Breaks down the fee by down payment amount, first versus subsequent use, and disability status.
National Guard and Reserve Eligibility: Clarifies eligibility criteria for Guard and Reserve members, which differs from active-duty timelines.
Surviving Spouse Information: Covers eligibility for surviving spouses of veterans — a category that’s often overlooked in standard VA loan discussions.
Best For
Any Florida buyer with military service history — veterans, active-duty service members, National Guard and Reserve members, and surviving spouses. Use this before initiating a no hard inquiry mortgage pre approval process so your VA status is confirmed and ready to factor into lender comparisons.
Pricing
Free. VA benefit — no cost to check eligibility or obtain a Certificate of Eligibility.
6. FEMA Flood Map Service Center — msc.fema.gov
Best for: Florida buyers checking a property’s flood zone designation before making an offer or locking a rate.
The FEMA Flood Map Service Center is the Federal Emergency Management Agency’s official flood map lookup tool — allowing any Florida buyer to check a specific property’s flood zone designation by address, completely free and without any login or credit information.
Where This Tool Shines
Florida has more properties in FEMA Special Flood Hazard Areas than most states, a direct consequence of the state’s low elevation and coastal geography. A property in Zone A, AE, or VE requires mandatory flood insurance as a condition of any federally backed loan — FHA, VA, USDA, or conventional loans sold to Fannie Mae or Freddie Mac. That insurance cost is not optional, and it directly affects your monthly housing payment and DTI calculation.
Running a flood zone check before you make an offer — not after — gives you the full picture of what that property actually costs to own. A payment that looks affordable without flood insurance can shift meaningfully once a mandatory policy is added. This is one of the most Florida-specific steps in the entire pre-purchase process, and it costs nothing to do it upfront.
Key Features
Property-Level Flood Zone Lookup: Search by address to get the specific flood zone designation for any Florida property.
SFHA Identification: Clearly identifies Special Flood Hazard Areas (Zones A, AE, VE) where flood insurance is a mandatory loan condition.
Official FIRM Links: Connects to the official Flood Insurance Rate Maps — the authoritative document lenders and insurers reference.
DTI Impact Awareness: Critical for accurate payment modeling — flood insurance must be included in housing cost calculations for SFHA properties.
Best For
Every Florida buyer, without exception. Flood zone status is not a detail to discover at closing. Run this check on any property you’re seriously considering before you request a formal Loan Estimate or lock any rate.
Pricing
Free. Federal government resource operated by FEMA — no registration required.
7. CFPB Mortgage Calculator — Owning a Home
Best for: Buyers stress-testing affordability across different rate and loan scenarios before contacting a lender.
The CFPB Mortgage Calculator is the Consumer Financial Protection Bureau’s interactive payment modeling tool — covering principal, interest, taxes, and insurance across different loan scenarios without requiring any login or credit information.
Where This Tool Shines
The value here is in scenario modeling before you’re in a lender conversation. Adjusting the interest rate input by 0.25% or 0.50% shows you exactly what a rate difference means in monthly payment terms — which is the right context for evaluating whether a DPA program’s potential rate premium is worth the upfront cash assistance. Running these scenarios in advance means you arrive at the lender conversation with informed questions rather than starting from zero.
The tool’s inclusion of property tax and homeowner’s insurance variables makes it more realistic than a simple principal-and-interest calculator. For Florida buyers, where insurance costs are among the highest in the country due to hurricane exposure and the state’s insurance market dynamics, having a tool that includes insurance in the payment estimate produces a more accurate affordability picture.
Key Features
Adjustable Inputs: Loan amount, interest rate, loan term, and down payment — all adjustable in real time.
Tax and Insurance Variables: Includes property tax and homeowner’s insurance estimates in the total payment calculation.
Principal vs. Interest Breakdown: Shows the amortization split over time — useful for understanding how equity builds at different loan terms.
Rate Scenario Stress-Testing: Ideal for modeling what happens to your payment if rates move before you lock.
Best For
Any buyer in the early research phase who wants to understand payment ranges before initiating a mortgage pre approval without hard pull. Pairs well with the FL Housing eligibility portal and HUD AMI lookup — run income eligibility first, then model the payment.
8. Florida Mortgage Maestro — Mortgage Calculator with Taxes and Insurance
Best for: Florida buyers who want payment modeling that reflects actual Florida costs — including insurance realities and homestead exemption context.
The Florida Mortgage Maestro Mortgage Calculator with Taxes and Insurance is a Florida-specific payment modeling tool built to reflect the real costs Florida buyers face — including property tax context, insurance variables, and homestead exemption considerations that a generic national calculator won’t surface.
Where This Tool Shines
Generic mortgage calculators use national averages for taxes and insurance. Florida buyers live in a different reality. Property insurance premiums in Florida are among the highest in the country, and that cost belongs in your payment model from day one — not as a surprise at closing. This calculator is built with that context in mind.
The homestead exemption framing is another Florida-specific detail that matters. Under Florida Statute 196.031, a primary residence qualifies for a $50,000 reduction in assessed value — which reduces the property tax base used to calculate your annual tax bill. The first year of ownership typically doesn’t reflect the exemption yet (it applies to the following tax year), so this tool helps buyers understand the difference between year-one taxes and stabilized taxes once the exemption is in place. That distinction affects your true housing cost calculation, and getting it right before you model affordability is the kind of detail that separates Florida-specific guidance from generic national content.
Key Features
Florida-Contextualized Tax and Insurance Inputs: Reflects the higher insurance market realities Florida buyers actually face — not national averages.
Homestead Exemption Context: Frames the Florida Statute 196.031 $50,000 assessed value reduction and its timing implications for year-one versus stabilized tax calculations.
No Login, No Credit Pull: Free, no personal information required.
Natural Pairing with NoTouch Pre-Approval: Model your payment range first, then initiate the soft credit pull mortgage eligibility check — in that order.
Florida Insurance Market Awareness: Helps buyers avoid underestimating insurance costs, which is one of the most common affordability miscalculations in Florida home purchases.
Best For
Florida buyers who want a realistic payment estimate before initiating the NoTouch pre-approval process. Particularly valuable for buyers coming from other states who are accustomed to lower insurance costs and may be significantly underestimating their monthly housing expense in Florida.
Pricing
Free tool available at FloridaMortgageMaestro.com — no registration required.
Frequently Asked Questions
What is a soft credit pull mortgage pre-approval?
A soft credit pull mortgage pre-approval is an eligibility assessment that uses a soft inquiry — which does not affect your credit score — to evaluate your loan options before you commit to a formal application. It gives you real information about program eligibility, estimated rates, and lender options without the credit score impact of a traditional hard inquiry.
Does a soft pull affect my credit score?
No. A soft inquiry is not reported to creditors and does not appear on your credit report as a negative item. It has no impact on your credit score. This is confirmed by the CFPB and the major credit bureaus. A hard inquiry, by contrast, is recorded and can lower your score by a small amount — which is why sequencing matters when you’re shopping for a mortgage.
What is Vantage Score 4.0 and how is it used for mortgage pre-approval?
Vantage Score 4.0 is a credit scoring model developed jointly by Equifax, Experian, and TransUnion. It can be used in soft-pull pre-screening contexts to assess a borrower’s general creditworthiness without triggering a hard inquiry. Florida Mortgage Maestro uses Vantage Score 4.0 in the NoTouch Credit Pull process to evaluate eligibility across the lender landscape before any hard pull is initiated.
How many lenders does Florida Mortgage Maestro shop with a soft pull?
The NoTouch Credit Pull process at Florida Mortgage Maestro shops across 100 or more lenders in a single session. This means one soft-pull eligibility check produces a multi-lender comparison — rather than requiring you to approach each lender individually, which would multiply your inquiry exposure.
Can I use a soft pull pre-approval with Florida down payment assistance programs?
Yes. The NoTouch Credit Pull process at Florida Mortgage Maestro is compatible with FL Assist ($10,000, 0% deferred), FL HLP ($10,000, 3% amortizing 15-year), Salute Our Soldiers, VA, FHA, USDA, and conventional programs. Eligibility is checked against the full program spectrum — not just one loan type — so you see the complete picture before committing to a direction.
Does Florida’s no state income tax help me qualify for a bigger mortgage?
Yes, in a meaningful and defensible way. Because Florida has no state income tax, your gross monthly income is not reduced by state withholding. Mortgage qualification uses gross income in the debt-to-income ratio calculation — so a Florida borrower earning the same gross income as a borrower in a high-income-tax state may have a better DTI profile on paper. This is a genuine financial advantage that Florida-specific mortgage guidance should account for explicitly.
When does the hard pull happen in the mortgage process?
A hard inquiry is required for final loan underwriting — it cannot be avoided at that stage. In the NoTouch Credit Pull process at Florida Mortgage Maestro, the hard pull does not happen until you have reviewed your options, selected a direction, and chosen to move forward with a formal application. The soft-pull eligibility stage comes first, giving you full information before you authorize the hard inquiry.
What credit score do I need for a soft pull mortgage pre-approval in Florida?
There is no minimum credit score required to initiate a soft-pull eligibility check — it’s an assessment, not an approval decision. Different loan programs have different minimum score requirements at the underwriting stage: FHA loans typically require a 580 FICO for 3.5% down, VA loans have no VA-set minimum (individual lenders set their own overlays), and conventional loans generally require a 620 or higher. The soft-pull process helps identify which programs you’re likely to qualify for given your current profile.
Which Approach Is Right for Your Situation
Here’s how to sequence these tools based on where you are in the process.
First-Time Florida Buyers: Start with the Florida Mortgage Maestro NoTouch Credit Pull pre-approval to understand your full lender landscape without a credit hit. Layer in the Florida Housing eligibility portal to confirm DPA program eligibility, and use the HUD AMI lookup to verify your income falls within program limits. Run the Florida Mortgage Maestro calculator to model your real monthly payment before you make an offer.
Veterans and Active-Duty Service Members: Begin with the VA Loan Eligibility Center to confirm your COE and entitlement status. Then initiate the NoTouch Credit Pull process to see how VA financing compares across 100+ lenders simultaneously. Florida veterans should note that the state’s no income tax advantage applies to VA DTI calculations just as it does for conventional and FHA scenarios.
Every Florida Buyer, Without Exception: Run the FEMA Flood Map Service Center check on any property you’re seriously considering before you request a Loan Estimate or lock a rate. Flood zone status directly affects your monthly housing cost and DTI — it is not a detail to discover at closing.
Homeowners Exploring Cash-Out Refinancing: The NoTouch Credit Pull process covers cash-out refinances to 90% LTV. Use the Florida Mortgage Maestro calculator to model the new payment scenario first, then initiate the soft-pull eligibility check to see what the lender landscape actually offers.
The soft pull mortgage broker process at Florida Mortgage Maestro is the only step in this list that simultaneously shops hundreds of lenders, checks real program eligibility, and protects your credit score — with no hard inquiry until you’re ready to lock. Everything else on this list helps you arrive at that conversation better prepared.
Your dream home in Florida is closer than you think. Get your credit-safe consultation today and discover the loan options that fit your life, backed by trusted guidance every step of the way. Start your no credit hit mortgage application today — contact Duane Buziak, NMLS #1110647, Coast2Coast Mortgage LLC NMLS #376205, licensed statewide in Florida.
4 Responses