
How to Calculate Total Mortgage Cost in Florida (2026)
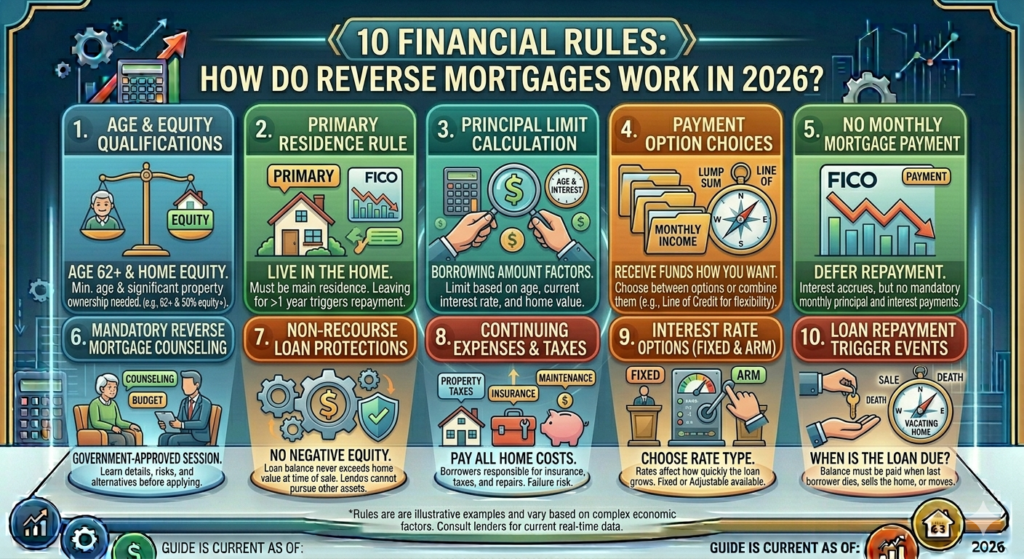
This guide explains how to calculate total mortgage cost in Florida by walking through every line item beyond the advertised rate, including property taxes, insurance, mortgage insurance, and HOA dues, so buyers can compare loan offers accurately.
How to Prepare a Foreign National Mortgage

Prepare a foreign national mortgage for a Florida property with documents, cash-to-close planning, and broker guidance that keeps your purchase moving.
7 Strategies to Weigh Assumable Mortgage Pros and Cons in Florida

This guide breaks down assumable mortgage pros and cons for Florida buyers and sellers, using real equity gap math, servicer approval steps, and FHA, VA, and USDA loan rules instead of headline rates. It gives seven concrete strategies to determine within a day or two whether assuming a mortgage is actually worth pursuing.
How Does the Mortgage Process Work in Florida? Step-by-Step Guide

This guide answers how does the mortgage process work in Florida, walking buyers through all seven stages, from soft credit pull pre-approval to underwriting and closing, with the typical 30-45 day timeline once under contract. It also explains where Florida-specific factors like flood zone checks, the homestead exemption, and state down payment assistance programs fit into the sequence.
VA Loan Versus Conventional Loan in Florida
Compare a VA loan versus conventional loan in Florida: costs, approval, condo rules, funding fees, and a clear path to choosing with confidence today.
Closing Cost Calculator for Florida Homes: What to Expect

A closing cost calculator for Florida homes only tells the full story when it accounts for documentary stamp tax, flood zone insurance, and state down payment assistance programs. This guide breaks down what generic national tools miss and how Florida buyers can get a more accurate estimate before closing.
Mortgage Approval With Tax Liens in Florida: A Step-by-Step Guide
This guide explains how mortgage approval with tax liens works in Florida, breaking down how federal, state, and county liens are treated differently in underwriting and the exact steps borrowers need to move from lien to closing table.
Mortgage Assumption Process Explained: How to Take Over a Seller’s Loan in Florida
The mortgage assumption process allows Florida buyers to take over a seller’s existing FHA, VA, or USDA loan — keeping the original interest rate and repayment terms instead of borrowing at today’s higher rates. This guide explains who qualifies, how servicer approval works, what the gap financing looks like, and why assumptions are a legitimate, lender-approved strategy worth understanding in Florida’s current market.
Florida Refinance Break Even: Know Your Number
Calculate your Florida refinance break even with closing-cost math, payment trade-offs, and Florida broker guidance before you make a move today.
6 Best Mortgage Lenders for the Mortgage Application Documents Needed in Florida in 2026
This guide breaks down the mortgage application documents needed for Florida home loans and compares 6 lenders, including Florida Mortgage Maestro and Movement, on how well each helps borrowers gather, organize, and submit paperwork without unnecessary credit hits.