

Updated for the 2026 Florida housing market. If you’ve typed “I’m struggling with my mortgage application” into a search bar at 11pm, you’re not alone — and you’re not out of options. Florida homebuyers face a specific set of hurdles in 2026: a rate environment that rewards preparation, flood zone insurance costs that inflate DTI, county-level income limits for assistance programs, and rising home prices in many metro markets.
The good news is that the right combination of tools can turn a stalled application into a clear path to closing. Florida’s lack of state income tax is a genuine DTI advantage that many applicants overlook entirely, and knowing how to frame that correctly can shift your qualifying numbers in meaningful ways. Whether you’re searching for a soft pull mortgage pre-approval, a no hard inquiry mortgage application, a mortgage pre-approval without hard pull, or simply a no credit hit eligibility check, there’s a right way to start without damaging the score you’re trying to protect.
A few key advantages available to Florida buyers in 2026 that you should know about before you read further:
- 500+ wholesale lenders accessible through Florida Mortgage Maestro’s broker model — one document package, one soft pull, maximum competition.
- 1,400+ five-star reviews from Florida buyers and homeowners who’ve closed through this process.
- VA loans to 500 FICO — qualifying veterans have more flexibility than many applicants realize.
- Dynamo DPA and Turbo DPA — proprietary down payment assistance programs that can help eligible buyers get to closing with little to nothing out of pocket at closing.
- FL Assist, FL HLP, and Salute Our Soldiers — Florida Housing Finance Corporation programs with current 2026 terms (verify at floridahousing.org before applying, as program terms can change).
This list covers tools purpose-built for buyers and homeowners who need to diagnose the problem, run real numbers, and move forward with confidence. Whether your obstacle is credit, down payment, debt-to-income ratio, or simply not knowing which loan program fits your situation, there’s a resource here for you. Note to site team: confirm OG meta tags (og:title, og:description, og:image) and Twitter card tags are fully populated on this page — this was a confirmed gap even in the portfolio’s highest-scoring article and must not recur. Start at #1.
1. Florida Mortgage Maestro — NoTouch Credit Pre-Approval
Best for: Florida buyers who want to check eligibility without a credit hit
Florida Mortgage Maestro is a Florida-licensed mortgage broker serving clients statewide, using Vantage Score 4.0 for a soft-pull eligibility check that won’t touch your credit score.
Where This Tool Shines
Most applicants don’t realize that a no hard inquiry mortgage pre-approval is even possible. Florida Mortgage Maestro’s NoTouch Credit process uses Vantage Score 4.0 — a soft inquiry — so your score stays intact during the eligibility review. That matters because multiple hard pulls during rate shopping can actually lower the score you’re trying to protect.
The broker model means one consultation shops hundreds of lenders simultaneously rather than requiring you to apply separately to each one. For applicants who’ve been denied elsewhere, that breadth of lender access is often the difference between a dead end and a workable path forward.
Key Features
NoTouch Credit Check: Vantage Score 4.0 soft pull — no credit hit during the eligibility review, making it a true no credit hit mortgage application process.
Multi-Lender Shopping: Hundreds of lenders accessed in a single consultation, maximizing the chance of finding a program that fits your specific profile.
Specialized Experience: First-time buyers, refinances, and applicants who have been denied elsewhere are all served — not just the easy files.
Cash-Out Refinances to 90% LTV: One of the higher cash-out thresholds available through broker channels, useful for homeowners with equity who need access to funds.
24/7 Availability and Fast Close Times: Designed for buyers on timelines, including those competing in active Florida markets.
Best For
Florida buyers who want to understand their options before committing to a hard pull. Also well-suited for applicants who’ve been turned down by a single bank and assume that’s the final answer — it often isn’t when a broker with access to hundreds of lenders is involved. Realtor referrals are available for buyers still searching for a home.
Pricing
No upfront cost for the consultation. Broker fees are disclosed on the Loan Estimate per federal law — no hidden charges, no surprises at closing.
2. CFPB Loan Estimate Explainer
Best for: Buyers who received a Loan Estimate and don’t know what they’re looking at
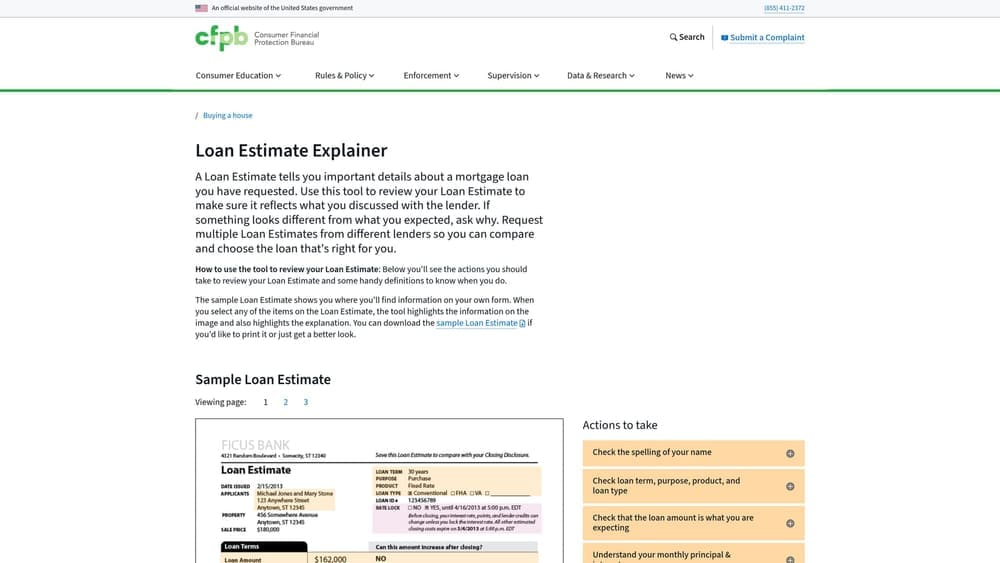
The CFPB Loan Estimate Explainer is the Consumer Financial Protection Bureau’s official interactive tool that breaks down every line of a Loan Estimate or Closing Disclosure.
Where This Tool Shines
One of the most common reasons mortgage applications stall is that borrowers don’t understand what they’ve been given. A Loan Estimate is a three-page federal document with dozens of line items — and knowing which fees are fixed versus which ones can be shopped is genuinely valuable information that many applicants never receive.
This tool is completely free, has no advertising, requires no account, and comes directly from the federal agency that writes the rules lenders must follow. That makes it a trustworthy reference when you’re comparing offers or questioning a fee that seems off.
Key Features
Line-by-Line Breakdown: Every section of the standard Loan Estimate form is explained in plain language with interactive annotations.
Fixed vs. Shoppable Fees: Identifies which closing costs are set by the lender and which ones you’re legally allowed to shop around for — a distinction that can save real money.
Government Source: No advertising, no lead capture, no upsell — just the information, from the agency that regulates the process.
Always Available: No account required, accessible 24/7 from any device.
Best For
Borrowers who have received a Loan Estimate and feel confused or uncertain about what they’re agreeing to. Also useful for comparing estimates from multiple sources to ensure you’re reading them on an apples-to-apples basis.
Pricing
Free. No registration required.
3. CFPB Owning a Home Mortgage Calculator
Best for: Diagnosing a DTI problem before it reaches a lender’s desk
The CFPB’s Owning a Home mortgage calculator goes beyond principal and interest to include taxes, insurance, and PMI — giving Florida buyers a realistic monthly payment figure to test against their actual debt-to-income ratio.
Where This Tool Shines
Most online calculators show you a principal and interest figure and call it a monthly payment. That number can be misleading by hundreds of dollars in Florida, where property taxes, homeowners insurance, and mandatory flood insurance for SFHA properties all contribute to the real PITI figure that lenders use to calculate DTI.
Florida’s no state income tax is a genuine qualifying advantage — a borrower earning $80,000 annually in Florida has more gross income available for housing expense than an equivalent borrower in a state with a 5–6% income tax. But you still need to know what that PITI figure actually is before you can frame that advantage correctly. This calculator helps you get there.
Key Features
Full PITI Calculation: Principal, interest, taxes, and insurance are all included — not just the base loan payment that understates the real number.
PMI Toggle: Buyers putting down less than 20% can model the PMI impact on their monthly obligation before it surprises them at closing.
Rate and Term Flexibility: Adjust rate, loan term, and down payment to model different scenarios and understand how each variable affects qualification.
Official Government Tool: No data harvesting, no lead capture, no follow-up sales calls — just the math.
Best For
Buyers trying to understand why their DTI is coming up short, or those who want to test different price points and down payment amounts before speaking with a broker. Also useful for homeowners considering a cash-out refinance who want to model the new payment before committing.
Pricing
Free. No account required.
4. Florida Housing Finance Corporation — FL Assist, FL HLP, and Salute Our Soldiers
Best for: Florida buyers who qualify for income-based down payment assistance
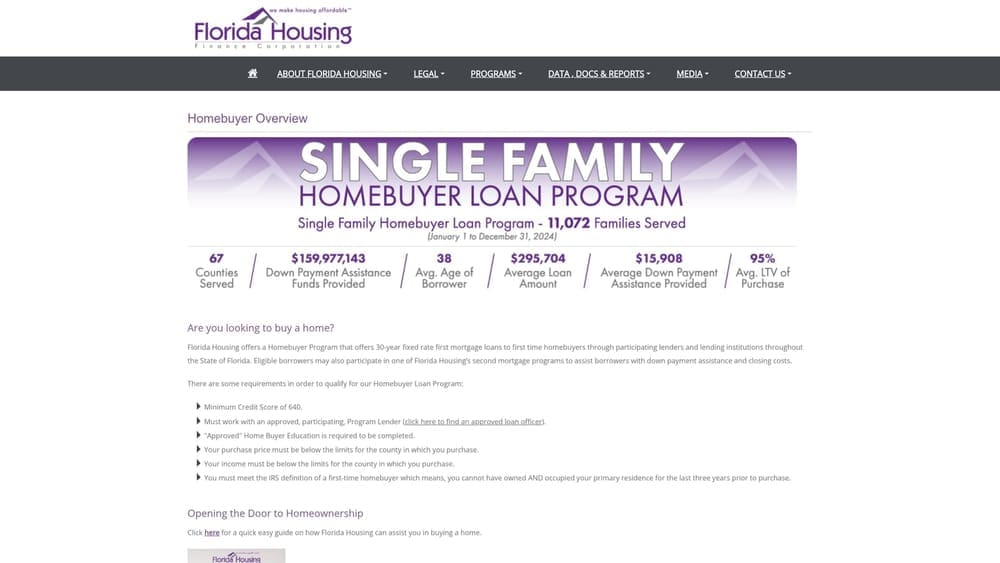
Florida Housing Finance Corporation is the state’s official housing finance agency, administering the FL Assist, FL HLP, and Salute Our Soldiers programs for eligible Florida buyers.
Where This Tool Shines
Down payment is one of the most common documented reasons a Florida mortgage application stalls. FL Assist and FL HLP both provide $10,000 in assistance, but they work differently — and understanding which one fits your situation requires running the numbers across three variables: the rate premium you accept to use the program, the $10,000 received, and how long you plan to stay in the home.
Here’s how that breakeven calculation works in practice. If using FL Assist adds 0.25% to the rate on a $300,000 loan, that rate premium costs approximately $45 per month extra in interest (using a simplified illustration — actual figures depend on your specific rate and loan terms). Divide the $10,000 DPA received by $45/month and the breakeven point falls around month 222, or roughly 18.5 years. If the buyer stays past that point, the DPA was net-positive. If the buyer sells or refinances sooner — which many Florida homeowners do — the deferred structure of FL Assist (no monthly payment, due on sale or refi) may still be advantageous because no cash left their pocket during ownership. FL HLP, with its 3% amortizing 15-year structure, adds a monthly payment but may carry a smaller rate premium depending on the lender. Always verify current program terms at floridahousing.org before making decisions — program availability and terms can change.
Key Features
FL Assist: $10,000 at 0% interest, fully deferred — no monthly payment required until the home is sold, refinanced, or transferred.
FL HLP: $10,000 at 3% interest, amortizing over 15 years with a monthly payment — a different structure suited to different buyer profiles.
Salute Our Soldiers: Veteran-specific down payment assistance through Florida Housing Finance Corporation, with competitive terms for eligible military borrowers.
County-Specific Income Limits: Eligibility is based on HUD Area Median Income by county and household size — the limits vary significantly across Florida’s 67 counties.
First Mortgage Pairing Requirement: These programs must be used with a Florida Housing-approved first mortgage — your broker needs to know how to structure this correctly.
Best For
First-time buyers in Florida whose primary obstacle is the down payment, particularly those whose income falls within county-specific AMI limits. Veterans should specifically ask about Salute Our Soldiers, which is often underutilized simply because applicants don’t know it exists.
Pricing
The assistance itself is free to apply for. It’s structured as a second mortgage, not a grant. Income and purchase price limits apply and are county-specific — verify current thresholds before assuming eligibility.
5. HUD Area Median Income (AMI) Lookup Tool
Best for: Verifying income eligibility for Florida assistance programs before applying
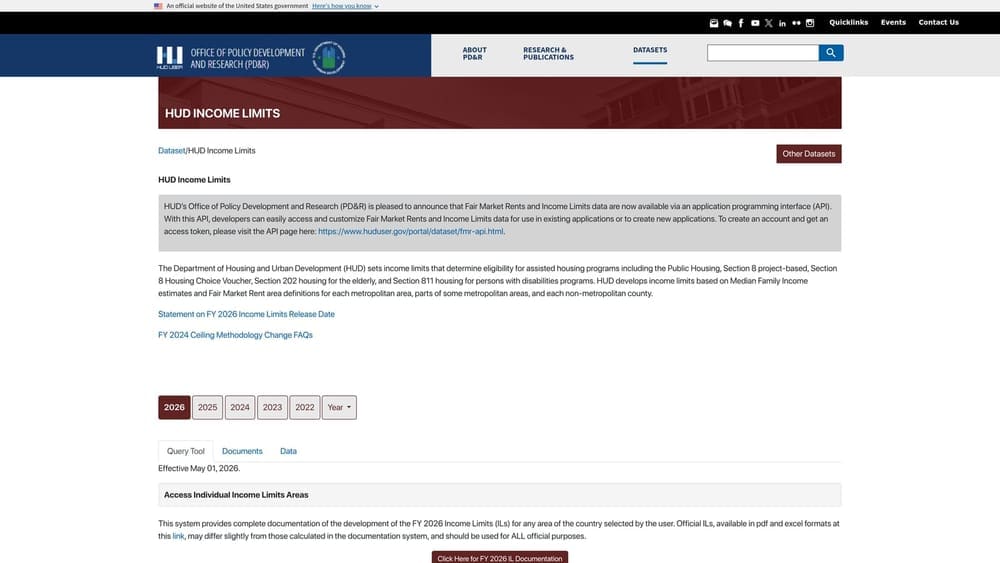
HUD’s Area Median Income dataset is the authoritative federal source for county-level AMI figures — the same data that determines whether a Florida buyer qualifies for FL Assist, FL HLP, FHA programs, and other income-restricted assistance.
Where This Tool Shines
Florida’s 67 counties have meaningfully different AMI thresholds. A household income that qualifies in one county may not qualify in another, and the limits adjust by household size. Many buyers assume they don’t qualify for assistance programs based on a rough guess — or assume they do qualify without actually checking. Either assumption can derail an application.
Because Florida has no state income tax, gross income figures used in AMI calculations aren’t reduced by state tax withholding. That’s a straightforward advantage: your gross qualifying income is the number that matters, and Florida borrowers keep more of it. Checking the HUD AMI tool before speaking with a broker ensures you’re having a conversation grounded in accurate eligibility data rather than estimates.
Key Features
County-Level Data: Specific AMI figures for every Florida county, not statewide averages that obscure meaningful local variation.
Household Size Adjustments: Figures are broken down for 1 through 8 person households, which directly affects program eligibility thresholds.
Annual Updates: HUD updates these figures annually, so the data reflects current program-year limits rather than outdated estimates.
Official Federal Source: The same dataset used by lenders, housing agencies, and program administrators — not a third-party approximation.
Best For
Any Florida buyer considering income-restricted assistance programs, particularly FL Assist, FL HLP, or FHA loans with income-based overlays. Check this before your consultation so you arrive with accurate data.
Pricing
Free. No account required.
6. FEMA Map Service Center
Best for: Florida buyers whose DTI is coming up short due to unaccounted flood insurance costs
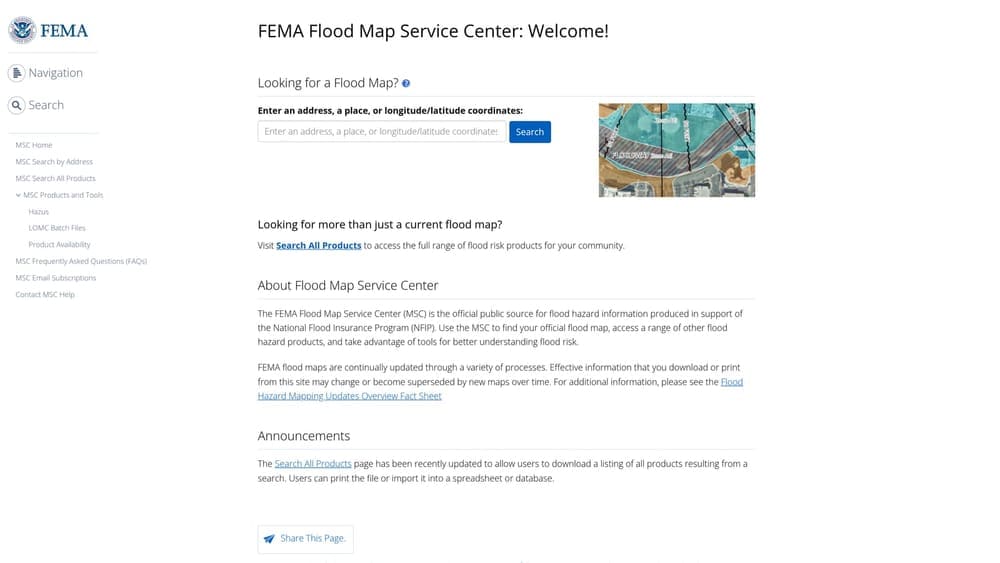
The FEMA Map Service Center is the official federal tool for looking up a specific property’s flood zone designation — a step that is genuinely critical in Florida, where mandatory flood insurance on SFHA properties adds a real monthly cost that must be included in DTI calculations.
Where This Tool Shines
Flood insurance is one of the most common hidden DTI inflators for Florida mortgage applicants. Properties located in a Special Flood Hazard Area (SFHA) require mandatory flood insurance as a condition of the mortgage — and that premium, which can range significantly depending on the property and coverage level, gets added to the monthly payment that lenders use to calculate DTI.
Many buyers discover this cost for the first time during underwriting, after they’ve already been pre-approved based on a payment estimate that didn’t include it. Checking the FEMA Map Service Center before making an offer — or before running DTI numbers — eliminates that surprise entirely. This is the same source used by lenders, appraisers, and title companies, so the designation you see is the one that will govern your loan.
Key Features
Property-Level Flood Zone Lookup: Search by address to see the specific flood zone designation for any property in Florida.
SFHA Identification: Clearly identifies whether a property falls in a Special Flood Hazard Area requiring mandatory flood insurance as a loan condition.
Official FEMA Source: The authoritative federal database used by the lending industry — not an estimate or approximation.
No Account Required: Free, immediate access with no registration.
Best For
Florida buyers who are surprised by their DTI calculation or who are purchasing in coastal areas, low-lying inland communities, or any area where flood zone designation is uncertain. Also useful for homeowners considering a refinance who want to understand whether their current flood insurance requirement is correctly reflected in their escrow.
Pricing
Free. No login or registration required.
7. AnnualCreditReport.com
Best for: Identifying credit errors before a single hard pull occurs
AnnualCreditReport.com is the only federally authorized website for free credit report access under the Fair Credit Reporting Act — the starting point for any Florida buyer who suspects credit issues are stalling their application.
Where This Tool Shines
A significant number of stalled mortgage applications trace back to errors on credit reports that the borrower has never reviewed. An account reported as delinquent that was actually paid, a balance that reflects a closed account, an address tied to someone else’s file — these are real, disputable errors that can suppress a qualifying score below program minimums. Identifying them before a lender pulls credit means you can dispute and correct them first, rather than discovering the problem after the hard inquiry has already landed.
This is the only site authorized by federal law for free reports. It’s not a third-party aggregator, it’s not a subscription service, and accessing your reports here is a soft inquiry that does not affect your credit score. For buyers preparing for a mortgage pre approval without hard pull, reviewing this first is the logical starting point.
Key Features
All Three Bureaus: Free reports from Equifax, Experian, and TransUnion — all three, because lenders typically review all three and a problem on one bureau affects your qualifying score.
Federally Authorized: Mandated under the Fair Credit Reporting Act (FCRA) — this is the official source, not an imitation site.
Soft Inquiry: Accessing your own report here does not affect your credit score — it’s a consumer pull, not a lender pull.
Dispute Starting Point: Reviewing your reports here gives you the documentation needed to initiate a formal dispute with any bureau before a lender sees the file.
Best For
Any Florida buyer who hasn’t reviewed their credit reports in the past 12 months, or anyone who suspects an error is holding their score below a program minimum such as FHA’s 580 threshold or VA’s more flexible guidelines. Do this before any lender runs credit.
Pricing
Free. Federally mandated access — no subscription required.
8. Florida Mortgage Maestro — Credit Restoration Resource
Best for: Buyers whose score is the documented reason their application stalled
Florida Mortgage Maestro’s Credit Restoration Resource is a dedicated pathway for buyers who are 3 to 12 months away from qualifying — designed to prepare borrowers for a soft pull mortgage broker consultation once their score reaches the right threshold.
Where This Tool Shines
Being told your credit score isn’t there yet doesn’t have to mean the conversation is over. The credit restoration pathway at Florida Mortgage Maestro is built specifically for mortgage qualification — not generic credit improvement advice, but targeted guidance aligned with the actual program minimums that matter in Florida. FHA loans have a documented minimum of 580 FICO for maximum financing; VA loans allow flexibility down to 500 FICO in some cases with specific lenders. Knowing which threshold you’re working toward changes the strategy.
What makes this resource particularly useful is the endpoint it’s designed to reach: a no credit hit mortgage application process once the score is ready. Rather than spending months improving a score only to damage it again with multiple hard pulls during rate shopping, the pathway connects directly to the NoTouch Credit soft-pull pre-approval when the borrower is ready. That continuity — from credit work to soft-pull eligibility check — is built into the process.
Key Features
Mortgage-Specific Guidance: Credit improvement advice tailored to program qualification thresholds, not generic financial wellness content.
Florida Program Awareness: FHA 580 minimum, VA flexibility to 500 FICO, and Florida Housing program requirements are built into the framework.
Direct Pathway to Soft-Pull Pre-Approval: Once score thresholds are met, the process connects directly to a no hard inquiry mortgage pre approval — protecting the score you worked to build.
No Hard Inquiry During the Process: The entire pathway is designed to avoid unnecessary hard pulls until you’re genuinely ready to move forward.
Best For
Florida buyers who have been told their score is too low, who are aware of specific derogatory items on their report, or who want a structured plan to reach mortgage qualification without guessing. Also useful for buyers who pulled their AnnualCreditReport.com reports (see #7) and found errors or patterns they need to address before applying.
Pricing
The resource itself is free. Credit restoration services vary depending on the specific situation — consult directly to understand what applies to your file.
Comparing All 8 Tools at a Glance
Here’s how each tool maps to the most common Florida mortgage application bottlenecks:
Tool | Primary Problem Solved | Cost | Florida-Specific? | Hard Pull Required?
Florida Mortgage Maestro NoTouch Pre-Approval | Finding the right lender and program | No upfront cost | Yes — statewide FL broker | No (Vantage Score 4.0 soft pull)
CFPB Loan Estimate Explainer | Understanding fees and what to negotiate | Free | No (federal tool) | No
CFPB Mortgage Calculator | Diagnosing DTI with full PITI | Free | No (federal tool) | No
Florida Housing Finance Corp. | Down payment gap (FL Assist, FL HLP, Salute Our Soldiers) | Free to apply | Yes — Florida programs only | Varies by first mortgage lender
HUD AMI Lookup Tool | Verifying income eligibility for assistance | Free | Yes — county-specific FL data | No
FEMA Map Service Center | Identifying flood insurance cost impact on DTI | Free | Yes — critical for FL properties | No
AnnualCreditReport.com | Identifying and disputing credit errors | Free | No (federal, all states) | No (soft/consumer pull)
FL Mortgage Maestro Credit Restoration | Building score to program minimums | Free resource | Yes — FL program thresholds | No (soft pull at end of process)
Frequently Asked Questions
Why did my mortgage application get denied in Florida?
The most common documented reasons are credit score below program minimums, debt-to-income ratio too high, insufficient down payment funds, or property issues identified during appraisal. In Florida specifically, flood insurance costs on SFHA properties are a frequent DTI inflator that applicants don’t account for until underwriting. A denial from one lender is not a final answer — a broker with access to hundreds of lenders may find a program that fits where a single bank could not.
What is a soft credit pull mortgage pre-approval?
A soft credit pull mortgage pre-approval uses a soft inquiry — such as Vantage Score 4.0 — to review your credit profile without triggering a hard inquiry on your credit report. Hard inquiries can lower your score by a few points and remain visible to other lenders for two years. A no hard inquiry mortgage pre approval lets you understand your eligibility and options without any impact to the score you’re trying to protect during the process.
How does Florida’s no state income tax help my DTI?
Debt-to-income ratio is calculated using gross income — your income before taxes. Florida has no state income tax, which means a borrower earning $80,000 annually in Florida has the full gross figure available for DTI purposes, without a state tax reduction. A borrower in a state with a 5–6% income tax effectively has less gross income supporting the same housing expense. For borderline DTI cases, a broker who understands how to frame this correctly can sometimes make the difference in qualification.
What is FL Assist and do I qualify?
FL Assist is a $10,000 down payment assistance program offered through the Florida Housing Finance Corporation at 0% interest, fully deferred — no monthly payment is required until the home is sold, refinanced, or transferred. Eligibility requires income at or below county-specific HUD AMI limits, a qualifying credit score, and use with a Florida Housing-approved first mortgage. Check your county’s current limits at huduser.gov and current program terms at floridahousing.org.
Does flood insurance affect my mortgage qualification?
Yes, directly. Properties in a FEMA-designated Special Flood Hazard Area (SFHA) require mandatory flood insurance as a condition of the mortgage. That premium is added to your monthly housing expense and included in the DTI calculation lenders use to approve or deny your application. If your DTI is coming up short, checking the FEMA Map Service Center at msc.fema.gov will confirm whether flood insurance is part of the equation — and how much it’s affecting your numbers.
What is the Florida Homestead Exemption and when does it apply?
Florida Statute 196.031 provides a Homestead Exemption that reduces a primary residence’s assessed value by $50,000 for property tax purposes. This reduces your annual property tax bill — which matters for escrow calculations on your mortgage. One important timing note: buyers won’t see this exemption reflected in their first year’s tax bill. Lenders may estimate taxes based on the pre-exemption assessed value, which can make the initial escrow estimate higher than the long-term reality. Understanding this distinction helps you plan for the first year’s payment accurately.
How do I check my credit before applying for a mortgage without hurting my score?
Use AnnualCreditReport.com — the only federally authorized source for free credit reports under the Fair Credit Reporting Act. Accessing your own report through this site is a soft inquiry and does not affect your score. You’ll receive reports from all three bureaus: Equifax, Experian, and TransUnion. Review them for errors, disputed balances, or unfamiliar accounts before any lender runs credit. This is the mortgage pre approval without hard pull preparation step that many applicants skip — and shouldn’t.
What income limits apply to Florida down payment assistance programs?
Income limits for FL Assist, FL HLP, and related Florida Housing programs are based on HUD Area Median Income (AMI) and vary by county and household size. Florida’s 67 counties have meaningfully different thresholds — what qualifies in a rural county may not qualify in Miami-Dade or Collier. Check current limits directly at huduser.gov for your specific county and household size, and verify current program terms at floridahousing.org before applying.
Which Tool Fits Your Situation?
If your obstacle is credit, start with AnnualCreditReport.com to review your reports for errors, then connect with Florida Mortgage Maestro’s credit restoration resource if your score needs structured work before you’re ready to apply. The endpoint of that process is a soft pull mortgage broker consultation — no credit hit until you’re genuinely prepared.
If your obstacle is down payment, the Florida Housing Finance Corporation’s FL Assist and FL HLP programs are the most direct path for eligible buyers. Run the three-variable breakeven (rate premium, $10,000 received, ownership timeline) before deciding which structure fits. Veterans should ask specifically about Salute Our Soldiers.
If your obstacle is DTI, start with the CFPB mortgage calculator to understand your full PITI number — including flood insurance if the property is in an SFHA. Check the FEMA Map Service Center to confirm flood zone status. And remember: Florida’s no state income tax is a genuine gross income advantage that a knowledgeable broker can frame correctly in your file.
If you’re not sure which obstacle is yours, that’s exactly what a no-credit-hit eligibility check is designed to answer. Duane Buziak, NMLS #1110647, is a Florida-licensed mortgage broker serving clients statewide through Coast2Coast Mortgage LLC, NMLS #376205, and a Scotsman Guide Top 114 Broker. The consultation costs nothing upfront, shops hundreds of lenders simultaneously, and starts with a soft pull that won’t affect your score.
Get your credit-safe consultation today and find out exactly where you stand — and what it takes to close.