

Most Florida homebuyers don’t realize that simply exploring mortgage options can affect their credit score. A hard inquiry from a lender can reduce your score by a few points, and that margin matters when you’re trying to qualify for the best rate on a Tampa condo, an Orlando starter home, or a Naples waterfront property.
The good news: a growing set of tools and services let you check eligibility, compare rates, and get pre-qualified without triggering a hard credit pull. This guide covers the best options available to Florida borrowers in 2026, from broker platforms using Vantage Score 4.0 soft pulls to federal resources that help you understand your credit standing before you ever speak with a lender.
Each tool is evaluated on credit protection method, Florida-specific utility, loan program coverage, and transparency of process. Florida Mortgage Maestro’s NoTouch Credit process is listed first because it offers the most comprehensive coverage for Florida borrowers — but every tool on this list serves a legitimate purpose depending on where you are in your homebuying journey.
1. Florida Mortgage Maestro — NoTouch Credit Pre-Qualification
Best for: Florida borrowers who want to check eligibility across hundreds of lenders without any credit impact.
Florida Mortgage Maestro is a Florida-licensed mortgage broker using Vantage Score 4.0 soft pull technology to check eligibility across hundreds of lenders in a single inquiry.
Where This Tool Shines
The structural advantage here is access. As a mortgage broker rather than a retail lender, Florida Mortgage Maestro shops your profile across hundreds of lenders simultaneously — something a single-lender institution like Rocket Mortgage, Movement Mortgage, or Freedom Mortgage cannot do. You get a broader picture of what’s available without triggering multiple hard pulls.
The Vantage Score 4.0 model used in the NoTouch Credit process can also incorporate non-traditional data points like rental payment history, which may benefit borrowers whose FICO scores don’t fully reflect their actual creditworthiness. For self-employed borrowers, investors, or anyone with a non-traditional income profile, this matters.
Key Features
Vantage Score 4.0 Soft Pull: Zero hard inquiry impact during the eligibility exploration phase — your score is protected throughout the pre-qualification process.
Hundreds of Lenders, One Inquiry: Your profile is checked against a broad lender network simultaneously, giving you competitive options without multiple credit hits.
FHA Down to 500 Credit Score: Per HUD guidelines (source: HUD.gov), FHA loans are available to borrowers with credit scores as low as 500 with appropriate down payment — and Florida Mortgage Maestro works with lenders who accept that threshold.
Non-QM and Bank Statement Loans: Self-employed Florida borrowers who can’t document income through traditional W-2s can qualify through bank statement or non-QM loan programs.
Cash-Out Refinance to 90% LTV: Above-average loan-to-value ceiling for borrowers looking to access equity in Florida properties.
Credit Restoration Pathway: Borrowers not yet ready to qualify can access in-house credit restoration guidance through Florida Mortgage Maestro’s credit restoration resource.
Best For
Florida homebuyers at any stage — first-time buyers in Orlando or Jacksonville, self-employed borrowers in Tampa or Sarasota, investors seeking DSCR loans, and anyone who wants to understand their real options before committing to a lender. Also well-suited for borrowers who’ve been turned down elsewhere and need a broader lender network.
Pricing
No cost for the pre-qualification inquiry. Broker fees are disclosed at the application stage per RESPA requirements. Available 24/7. Florida only.
2. AnnualCreditReport.com — Free Federal Credit Report Access
Best for: Reviewing your full credit file before approaching any lender, with zero credit impact.
AnnualCreditReport.com is the only federally authorized source for free credit reports from all three major bureaus, providing your complete credit file without any inquiry impact.
Where This Tool Shines
Before you talk to any lender — broker or retail — you should know exactly what’s in your credit file. AnnualCreditReport.com gives you the full picture: open accounts, payment history, derogatory marks, collections, and public records. This is your baseline, and reviewing it costs you nothing in score impact.
The practical value for Florida homebuyers is catching errors before a lender does. Credit report errors are more common than many borrowers expect, and disputing an inaccurate derogatory mark before applying can meaningfully improve your qualifying rate. Weekly free reports are currently available from all three bureaus — verify the current policy at the time you access the site.
Key Features
All Three Bureau Reports: Access to Equifax, Experian, and TransUnion reports in a single authorized portal.
Zero Credit Impact: Accessing your own report is not a credit inquiry under the Fair Credit Reporting Act — your score is completely unaffected.
Full Account Detail: Unlike score-only tools, you see the complete file — account history, balances, payment patterns, and any derogatory items.
Federally Mandated: Authorized under the Fair Credit Reporting Act (FCRA) and confirmed by the CFPB at ConsumerFinance.gov as the only legitimate free report source.
Weekly Reports Currently Available: Frequency of free access has expanded — verify current availability at the site directly.
Best For
Every Florida homebuyer, without exception, before beginning any mortgage process. This is the starting point for understanding your credit position, identifying errors, and preparing for conversations with lenders or brokers.
Pricing
Completely free — federally mandated under the FCRA. No subscription, no credit card required.
3. Credit Karma — Ongoing Score Monitoring with Soft Pull
Best for: Tracking credit score trends over time and understanding which factors affect mortgage eligibility.
Credit Karma is a free credit monitoring platform that provides ongoing VantageScore updates from TransUnion and Equifax using soft pulls only.
Where This Tool Shines
AnnualCreditReport.com gives you a snapshot. Credit Karma gives you a trend line. For Florida borrowers who are actively working to improve their credit profile before applying for a mortgage, monitoring score movement over weeks and months is genuinely useful. You can see whether paying down a credit card balance actually moved the needle, or whether a new account opened six months ago is still affecting your profile.
One important distinction: Credit Karma uses VantageScore, not FICO. Most mortgage lenders use FICO scores for underwriting decisions. The scores you see on Credit Karma may differ from what a lender pulls — sometimes meaningfully. Use Credit Karma as a directional indicator and trend tracker, not as a definitive pre-qualification number.
Key Features
Free VantageScore Monitoring: Ongoing score updates from TransUnion and Equifax at no cost — soft pull only, no credit impact.
Factor Analysis: The platform identifies which specific factors (credit utilization, payment history, account age) are helping or hurting your score.
Change Alerts: Notifications when something changes in your credit file — useful for catching unauthorized activity before it compounds.
Mortgage Pre-Qualification Offers: Pre-qualification offers shown on the platform use soft inquiries at the initial stage. Note that proceeding to a full application with any lender will trigger a hard pull.
Score Simulator: Allows you to model how specific actions (paying off a balance, opening a new account) might affect your score.
Best For
Florida borrowers in the preparation phase who want to track score improvement over time, understand their credit profile in detail, and identify specific actions that could strengthen their mortgage application before approaching a lender.
Pricing
Free. Credit Karma is owned by Intuit and generates revenue through financial product recommendations. No cost to the borrower for monitoring features.
4. CFPB Explore Rates Tool — Anonymous Rate Research
Best for: Understanding realistic rate ranges by loan type and credit profile without providing any personal information.
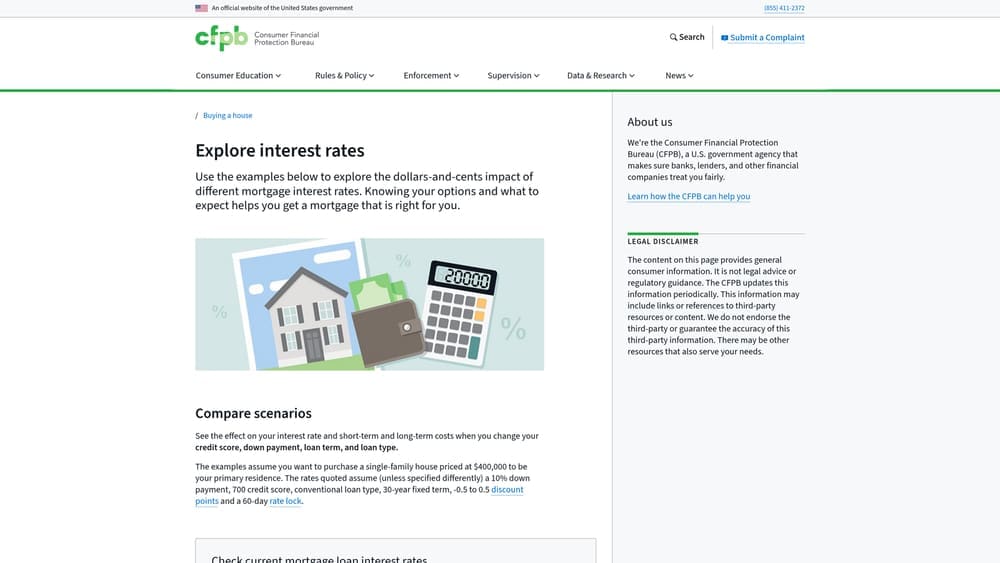
The CFPB Explore Rates Tool is a completely anonymous government resource showing mortgage rate ranges by loan type, credit score range, down payment, and state — with zero personal data required.
Where This Tool Shines
This tool is genuinely underused. Before you talk to a single lender, you can enter your approximate credit score range, down payment amount, loan size, and state (Florida), and see realistic rate ranges based on actual lender data reported to the CFPB. No name, no Social Security number, no phone number — nothing.
For Florida borrowers, this is valuable context. If you’re looking at a $400,000 home in Orlando with a 720 credit score and 10% down, the CFPB tool gives you a defensible benchmark before you start comparing lender quotes. It won’t tell you your exact rate, but it tells you whether the quote you’re being offered is in a reasonable range.
Key Features
Completely Anonymous: No personal data collected, no account required, no credit inquiry of any kind.
Florida-Specific Filtering: Rate ranges are filterable by state, which matters because Florida’s market conditions, flood insurance requirements, and property tax dynamics affect lender pricing.
Loan Type Coverage: Shows rate ranges for 30-year fixed, 15-year fixed, 5/1 ARM, and FHA loan types.
Government Source: Data comes from actual lender rate submissions to the CFPB — not sponsored content or advertiser rates.
Educational Context: The tool explains how different factors (credit score, down payment, loan term) affect rate — useful for borrowers learning the landscape.
Best For
Any Florida borrower who wants to understand rate ranges before engaging with lenders, or who wants to benchmark a quote they’ve already received. Particularly useful for first-time buyers who have no prior frame of reference for what mortgage rates look like.
Pricing
Free. Government resource maintained by the Consumer Financial Protection Bureau.
5. Credible — Soft Pull Rate Comparison Marketplace
Best for: Comparing personalized rate estimates from multiple lenders using a soft pull before committing to a full application.
Credible is a mortgage rate comparison marketplace that uses a soft pull to show personalized rate estimates from multiple lenders without triggering a hard inquiry at the initial stage.
Where This Tool Shines
Where the CFPB tool shows anonymous rate ranges, Credible shows personalized estimates tied to your actual profile — still using a soft pull. You enter your information once and receive competing rate offers from multiple lenders side by side. This is meaningfully different from going to each lender individually, which would generate multiple hard inquiries.
The critical caveat: the soft pull applies to the comparison stage only. When you select a lender and proceed to a full application, that lender will conduct a hard pull. The CFPB confirms that multiple mortgage hard inquiries within a 45-day window are typically treated as a single inquiry under FICO scoring models (source: CFPB.gov), which reduces the score impact of rate shopping — but Credible’s initial soft pull means you can see your options before reaching that stage.
Key Features
Soft Pull at Comparison Stage: Personalized rate estimates without a hard inquiry — your score is protected during the shopping phase.
Multiple Lender Comparison: View competing offers side by side in a single session rather than applying separately to each lender.
Florida Coverage: Available to Florida borrowers across loan types including conventional and FHA products.
Transparent Process: Credible clearly distinguishes between the soft pull comparison stage and the hard pull that follows a formal application with a chosen lender.
Best For
Florida borrowers who are ready to compare real rate offers and want a structured marketplace to do so before committing to a single lender. Most useful in the mid-to-late research phase, after you’ve reviewed your credit report and have a clear picture of your profile.
Pricing
Free to use the comparison tool. Credible earns fees from lenders when a borrower proceeds to application — no direct cost to the borrower for the rate comparison service.
6. Rocket Mortgage Pre-Qualification — National Brand Soft Pull Option
Best for: Borrowers who prefer a fully digital, self-service pre-qualification experience with a nationally recognized brand.
Rocket Mortgage is a large national direct-to-consumer lender that offers a soft pull pre-qualification option at the initial stage of its online application process.
Where This Tool Shines
Rocket Mortgage’s pre-qualification flow is polished, fast, and fully digital — useful for borrowers who want to understand their eligibility quickly without speaking to anyone. The soft pull at the pre-qualification stage means your score isn’t impacted during that initial exploration.
The structural distinction worth understanding: Rocket Mortgage is a single lender, not a broker. When you pre-qualify with Rocket, you’re seeing what Rocket specifically can offer based on its own products and guidelines. A mortgage broker like Florida Mortgage Maestro checks that same profile against hundreds of lenders simultaneously, which often produces more competitive options — particularly for borrowers with non-standard profiles or those seeking FHA, VA, or non-QM products that Rocket may not offer or may price less competitively. This is a structural difference, not a quality judgment.
Key Features
Soft Pull Pre-Qualification: Initial eligibility check uses a soft pull — no credit impact at the exploration stage.
Fully Digital Process: End-to-end online application without requiring a phone call or in-person meeting.
Fast Turnaround: Pre-qualification results delivered quickly through the online platform.
Conventional and FHA Products: Covers standard loan programs for Florida borrowers.
Best For
Borrowers who want a fast, self-service digital experience and are comfortable with a single-lender option. Also useful as a comparison benchmark — if you pre-qualify with Rocket, you can bring that offer to a broker to see whether a broader lender search produces better terms.
Pricing
No cost for pre-qualification. Lender fees and origination costs apply at the full application and closing stage.
7. LendingTree — Multi-Lender Marketplace with Initial Soft Pull
Best for: Generating multiple competing lender offers in a single session to compare rates and terms.
LendingTree is a mortgage marketplace aggregator that connects borrowers with multiple lenders and uses a soft pull at the initial inquiry stage.
Where This Tool Shines
LendingTree’s model is built around competition — the idea being that multiple lenders bidding for your business produces better terms than approaching a single lender directly. The initial inquiry uses a soft pull, meaning you can enter your information and receive multiple competing offers without an immediate credit impact.
Florida borrowers should be aware of one practical consideration: LendingTree is a lead generation platform, and lender follow-up can be persistent. Once you submit your information, multiple lenders may contact you. This is worth knowing in advance. Additionally, while the initial LendingTree inquiry is soft, each lender you choose to proceed with will conduct its own hard pull at the full application stage. Rate shopping within a 45-day window helps consolidate that impact under FICO’s inquiry grouping rules.
Key Features
Multiple Competing Offers: One inquiry generates offers from multiple lenders, creating a competitive dynamic that can benefit borrowers.
Soft Pull at Initial Stage: Your credit score is not impacted during the initial marketplace inquiry.
Broad Loan Type Coverage: Conventional, FHA, VA, and jumbo products are typically represented across LendingTree’s lender network.
Florida Market Coverage: Multiple lenders in the network serve Florida borrowers across major markets.
Best For
Borrowers who want to generate competing offers quickly and are comfortable managing follow-up from multiple lenders. Most effective when used as a rate benchmark alongside a broker consultation rather than as a standalone decision tool.
Pricing
Free for borrowers. LendingTree earns referral fees from lenders — no direct cost to the borrower for the comparison service.
8. HUD Housing Counseling — Pre-Purchase Guidance Without Any Credit Pull
Best for: First-time Florida homebuyers who want expert, unbiased mortgage guidance before approaching any lender.
HUD-Approved Housing Counseling connects Florida borrowers with HUD-certified counselors who provide pre-purchase guidance at no cost — with zero credit inquiry of any kind.
Where This Tool Shines
HUD-approved housing counselors are not lenders and have no financial stake in which loan you choose. They can walk you through your credit report, explain loan program options, help you understand what a realistic budget looks like given Florida’s property tax variations and coastal insurance costs, and prepare you for the mortgage process — all without touching your credit.
Florida has multiple HUD-approved counseling agencies across major markets. For a first-time buyer in Jacksonville trying to understand the difference between FHA and conventional financing, or a Tampa borrower trying to figure out how flood insurance affects their monthly payment, a HUD counselor provides genuinely neutral guidance. Source: HUD.gov.
Key Features
Zero Credit Impact: No credit inquiry of any kind — counselors review your situation without pulling your credit file.
HUD-Certified Neutrality: Counselors are federally certified and have no commission interest in your loan decision.
Florida Agency Network: Multiple HUD-approved agencies serve Florida borrowers across Tampa, Orlando, Jacksonville, Miami, and other markets.
Loan Program Education: Counselors explain FHA, conventional, VA, and USDA program differences in plain language.
Budget and Affordability Analysis: Helps borrowers understand realistic purchase price ranges given income, debts, and Florida-specific costs like flood insurance and county property taxes.
Best For
First-time Florida homebuyers who want to understand the mortgage landscape before engaging with any lender, and borrowers who feel they need more education before making program decisions. Also valuable for borrowers whose credit needs work and who want a clear roadmap before applying.
Pricing
Free or low-cost. HUD-approved counseling is available at no charge through many agencies. Verify fees directly with the specific agency when scheduling.
9. FICO Score Open Access — Lender-Provided Score Monitoring
Best for: Borrowers who already have a credit card or bank account that provides free FICO score access — the same scoring model most mortgage lenders use.
FICO’s Open Access program allows participating financial institutions to share your actual FICO score with you at no charge, giving you access to the score most mortgage lenders use for underwriting — without any additional credit inquiry.
Where This Tool Shines
Here’s a practical distinction that matters for mortgage planning: Credit Karma shows your VantageScore. Most mortgage lenders use FICO. The gap between these two scores can be meaningful — sometimes 20 to 40 points in either direction depending on your credit profile. FICO’s Open Access program, available through many major credit card issuers and banks, lets you see your actual FICO score for free through your existing account.
For Florida borrowers preparing to apply for a mortgage, knowing your FICO score in advance is more predictive of lender decisions than VantageScore alone. Check whether your current bank or credit card issuer participates in FICO Open Access — many do, including several major issuers. This gives you the most relevant benchmark before any lender conversation.
Key Features
Actual FICO Score: The same scoring model used by the majority of mortgage lenders — more directly relevant to mortgage underwriting than VantageScore.
No Additional Inquiry: Delivered through your existing financial institution relationship — no new credit pull required.
Score Factor Explanation: FICO Open Access includes an explanation of the top factors affecting your score, helping you identify what to address before applying.
Available Through Existing Accounts: Many major credit card issuers and banks participate — check your current accounts before signing up for a new monitoring service.
Best For
Florida borrowers who want to know their actual FICO score before approaching any lender, and who want to bridge the gap between VantageScore monitoring tools and the score a mortgage underwriter will actually see.
Pricing
Free through participating financial institutions. Verify availability through your current bank or credit card issuer. FICO also offers paid score access directly at MyFICO.com for borrowers whose institutions don’t participate.
Rate Context: What Your Credit Score Costs You in Florida
Understanding why credit score protection matters requires seeing the numbers. The table below illustrates how rate differences translate to monthly payment differences on a representative Florida loan amount. These figures are illustrative estimates only — actual rates vary by borrower profile, lender, loan program, and current market conditions.
Illustrative Rate and Payment Comparison — $350,000 Loan Amount, 30-Year Fixed
Rate: 6.50% | Est. Monthly P&I: ~$2,212 | Annual Interest Cost: ~$22,750 (Year 1)
Rate: 7.00% | Est. Monthly P&I: ~$2,329 | Annual Interest Cost: ~$24,500 (Year 1)
Rate: 7.50% | Est. Monthly P&I: ~$2,447 | Annual Interest Cost: ~$26,250 (Year 1)
Illustrative estimates only. Actual rates vary by borrower profile, lender, loan type, and market conditions. These figures do not include property taxes, insurance, or HOA fees. Contact a licensed mortgage professional for personalized rate quotes.
The difference between a 6.50% and a 7.50% rate on a $350,000 loan is approximately $235 per month. Over 12 months, that’s roughly $2,820. Over five years, it exceeds $14,000. Protecting your credit score during the exploration phase — so you qualify for the best possible rate — is not a minor consideration.
Breakeven Math: When Rate Shopping Pays Off
For borrowers considering a refinance, or evaluating whether to spend time improving their credit before applying, the breakeven calculation is straightforward. Here is the worked math using representative figures:
Scenario: Refinancing a $350,000 Florida mortgage from 7.50% to 6.50%.
Step 1 — Calculate monthly savings: $2,447 (payment at 7.50%) minus $2,212 (payment at 6.50%) = $235 per month in savings.
Step 2 — Estimate closing costs: Refinance closing costs typically range from $3,000 to $6,000 depending on loan size, lender, and Florida county. Using a midpoint of $4,500.
Step 3 — Calculate breakeven: $4,500 ÷ $235 = approximately 19 months to breakeven.
Step 4 — Evaluate: If you plan to remain in the property for more than 19 months after refinancing, the refinance produces net savings. If you plan to sell or refinance again before month 19, the closing costs may not be recovered.
These figures are illustrative. Actual closing costs, rates, and savings will vary. Verify current rates and costs with a licensed Florida mortgage professional before making any refinancing decision.
Frequently Asked Questions
Q: Does checking my mortgage eligibility hurt my credit score?
It depends on the type of inquiry. A soft pull — used by tools like Florida Mortgage Maestro’s NoTouch Credit process, Credit Karma, and the initial stages of Credible and LendingTree — does not affect your credit score. A hard pull, which occurs when you formally apply with a lender, is recorded on your credit file and can reduce your score by a small amount. Per FICO’s published guidance (source: MyFICO.com), a single hard inquiry typically reduces a score by fewer than 5 points for most people, though impact varies by credit profile.
Q: What is the difference between VantageScore and FICO?
VantageScore and FICO are both credit scoring models, but they use different algorithms and weighting systems. Most mortgage lenders use FICO scores for underwriting decisions. VantageScore (used by Credit Karma and Florida Mortgage Maestro’s Vantage Score 4.0 soft pull) is useful for monitoring trends and soft pull eligibility checks, but borrowers should be aware that the score a lender sees may differ from their VantageScore. Vantage Score 4.0 specifically can incorporate non-traditional data like rental payment history, which may benefit certain borrowers.
Q: If I apply with multiple lenders, will I get multiple hard inquiries?
Not necessarily. The CFPB confirms that multiple mortgage-related hard inquiries within a 45-day window are typically treated as a single inquiry by FICO scoring models (source: CFPB.gov). This means rate shopping — applying with several lenders to compare offers — has limited additional credit score impact when done within that window. Using a broker like Florida Mortgage Maestro further reduces this concern because a single inquiry accesses hundreds of lenders simultaneously.
Q: What credit score do I need to qualify for a Florida mortgage?
It depends on the loan program. FHA loans are available with credit scores as low as 500 with a 10% down payment, or 580 with a 3.5% down payment, per HUD guidelines (source: HUD.gov). Conventional loans typically require a minimum of 620, though better rates are available at higher score tiers. VA loans have no official minimum score requirement set by the VA (source: VA.gov), though individual lenders set their own overlays. Non-QM and bank statement loans have flexible criteria that vary by lender.
Q: Does Florida Mortgage Maestro serve all of Florida?
Yes. Florida Mortgage Maestro serves borrowers throughout the state of Florida, including Tampa, Orlando, Jacksonville, Miami, Naples, Sarasota, and surrounding areas. Services are limited to the state of Florida.
Q: What is the Florida conforming loan limit in 2026?
The conforming loan limit for single-family homes in most Florida counties is $806,500 for 2026. High-cost county exceptions apply, including Monroe County (Florida Keys area). Verify current limits at FHFA.gov at the time of your application, as limits are subject to annual adjustment.
Which Tool Is Right for You
The right starting point depends on where you are in the process. Here’s a practical breakdown by borrower situation.
If you’re just starting out and want to understand your options: Begin with AnnualCreditReport.com to review your full credit file, then use the CFPB Explore Rates Tool to understand realistic rate ranges for your profile — both completely free, both zero credit impact.
If you’re actively preparing to buy in the next 3 to 6 months: Florida Mortgage Maestro’s NoTouch Credit pre-qualification gives you a real eligibility assessment across hundreds of lenders using Vantage Score 4.0 — no credit hit, no commitment, and a clear picture of your actual options in the Florida market.
If you’re self-employed or have non-traditional income: Florida Mortgage Maestro’s access to non-QM and bank statement loan programs is a meaningful structural advantage over retail lenders like Rocket Mortgage or Movement Mortgage, which primarily serve W-2 borrowers through conventional and government-backed programs.
If your credit needs work before you can qualify: Start with AnnualCreditReport.com and Credit Karma to understand your current position, then connect with Florida Mortgage Maestro’s credit restoration pathway or a HUD-approved housing counselor for a structured improvement plan.
If you want to benchmark a rate you’ve already been quoted: The CFPB Explore Rates Tool and Credible both let you check whether an offer is competitive without triggering additional hard inquiries.
Florida’s housing market has distinct dynamics — from the flood insurance exposure in coastal Collier, Lee, and Pinellas counties, to the property tax variation between Miami-Dade and Hillsborough, to the absence of state income tax that improves effective affordability compared to other states. Working with a Florida-specific broker who understands these factors, rather than a national platform that treats all markets identically, can make a material difference in the loan you qualify for and the terms you receive.
Get your credit-safe consultation today and find out what you qualify for across hundreds of Florida lenders — with no credit impact, no obligation, and no guesswork.
Legal Disclaimer: This article is for educational purposes only and does not constitute a commitment to lend or an offer of credit. All loans are subject to credit approval, underwriting guidelines, and lender requirements. Rates and terms are subject to change without notice. Credit score impact varies by individual. FHA loan information sourced from HUD.gov. VA loan information sourced from VA.gov. CFPB rate and inquiry information sourced from ConsumerFinance.gov. FHFA conforming loan limits sourced from FHFA.gov. Florida Mortgage Maestro services are available in the state of Florida only. NMLS #1110647.
Duane Buziak, Mortgage Maestro | NMLS: 1110647 | Licensed in FL | VA Broker of the Year 2024-2025 | Top 1% Nationwide | Coast2Coast Mortgage | DuaneBuziakMortgageMaestro.com | (804) 212-8663